
Insurance claims
We Bill Your Insurance Directly
On covered water and mold claims, we document the loss the way adjusters need to see it, work with your carrier, and send the bill to them instead of you. You still pay your deductible. Filing a claim isn't required, though, and we take plenty of residential work that homeowners pay for themselves.
Insurance
We work with your insurance, and we bill them directly
- 01
Call us
We answer, ask what happened, and get a crew moving. Same-day emergency response on active water.
- 02
We document everything
We take moisture readings and photos and write up a scope of work before drying starts, so your adjuster has the file from day one.
- 03
We bill your insurer directly
We work directly with your insurance company on covered water and mold claims, so you're not fronting the full cost and chasing reimbursement.
Your deductible is still yours to cover. Your declarations page or your agent has the exact number, and we ask for it before any work starts rather than after. You also don't need a claim to hire us. Plenty of our jobs are paid directly by the homeowner, and after the free inspection you get a written estimate to make that decision with.
Not insurance advice. We're a restoration contractor, not a public adjuster or insurance agent. Coverage decisions belong to your insurer, so confirm anything about your policy with your agent or adjuster.
Start to finish
How a claim works
- 01
Call us
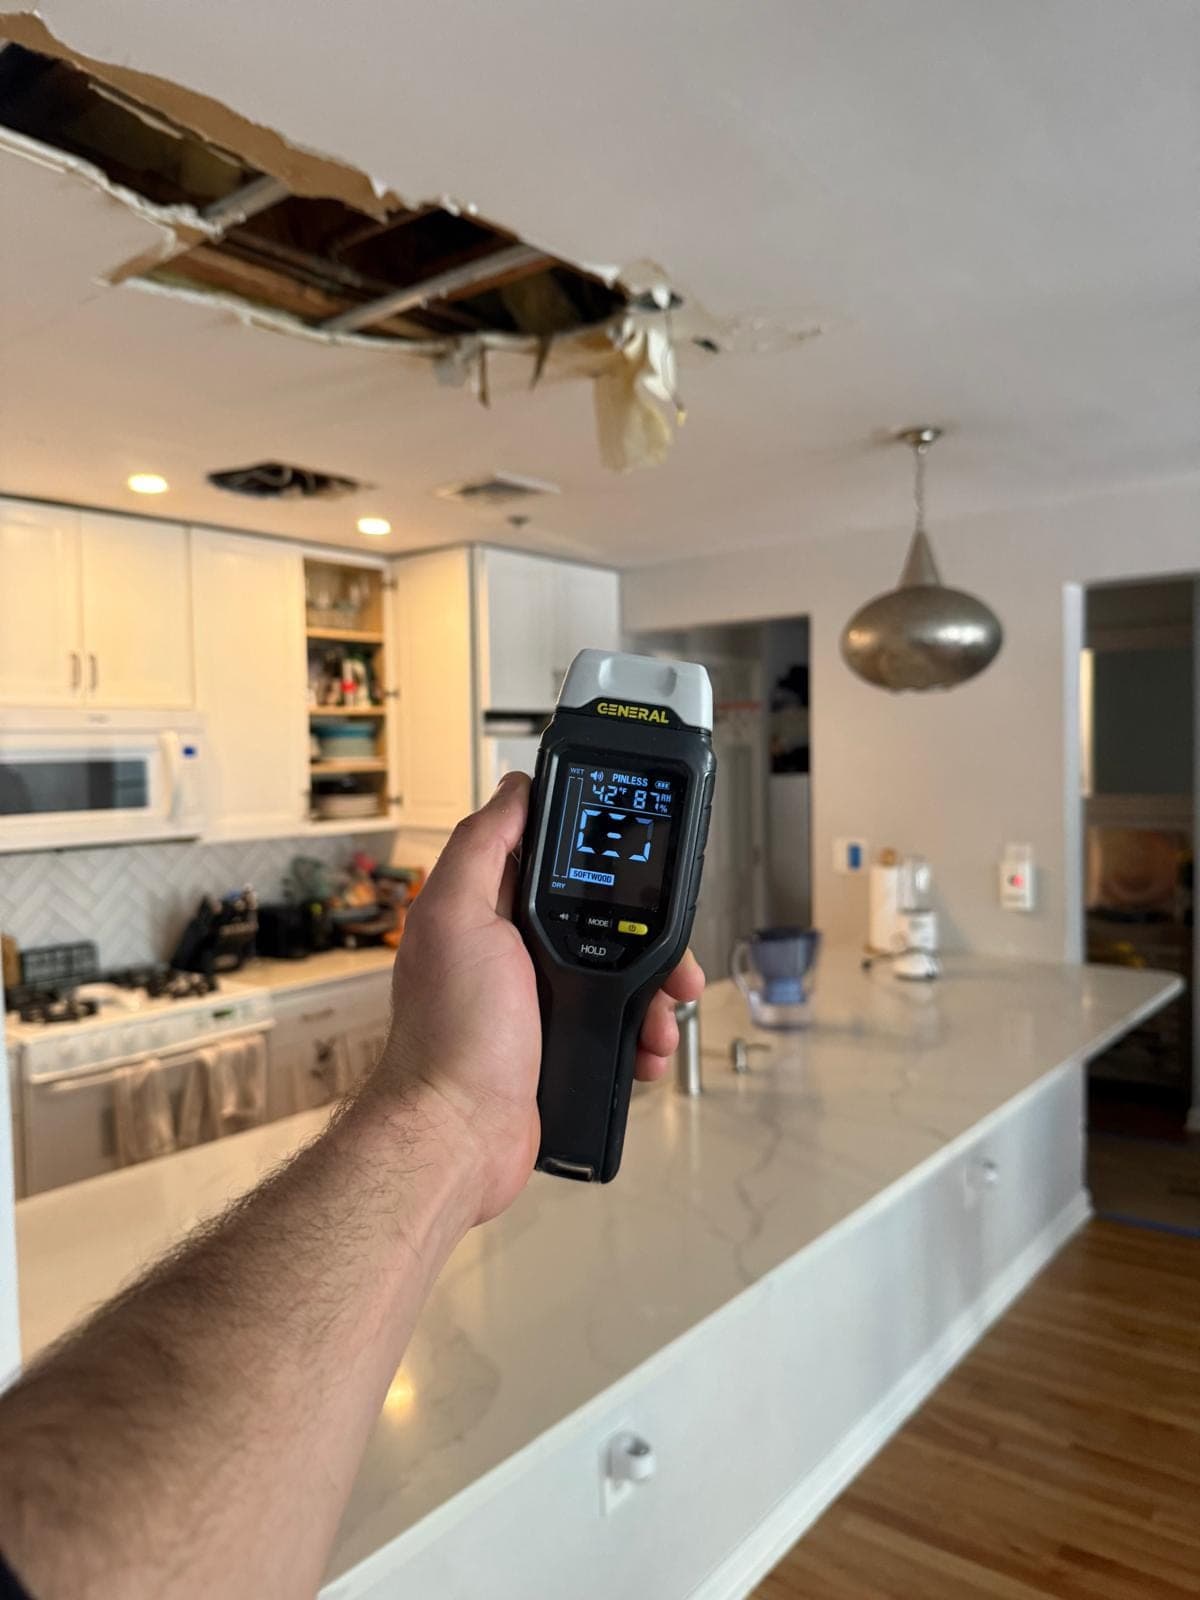
(845) 262-6530. For active water we dispatch the same day; for everything else we schedule the free inspection around you. Either way, don't wait for the adjuster to start mitigation. Nearly every policy requires you to take reasonable steps to prevent further damage, and we document as we work, so the adjuster sees exactly what condition the property was in.
- 02
Free inspection & documentation
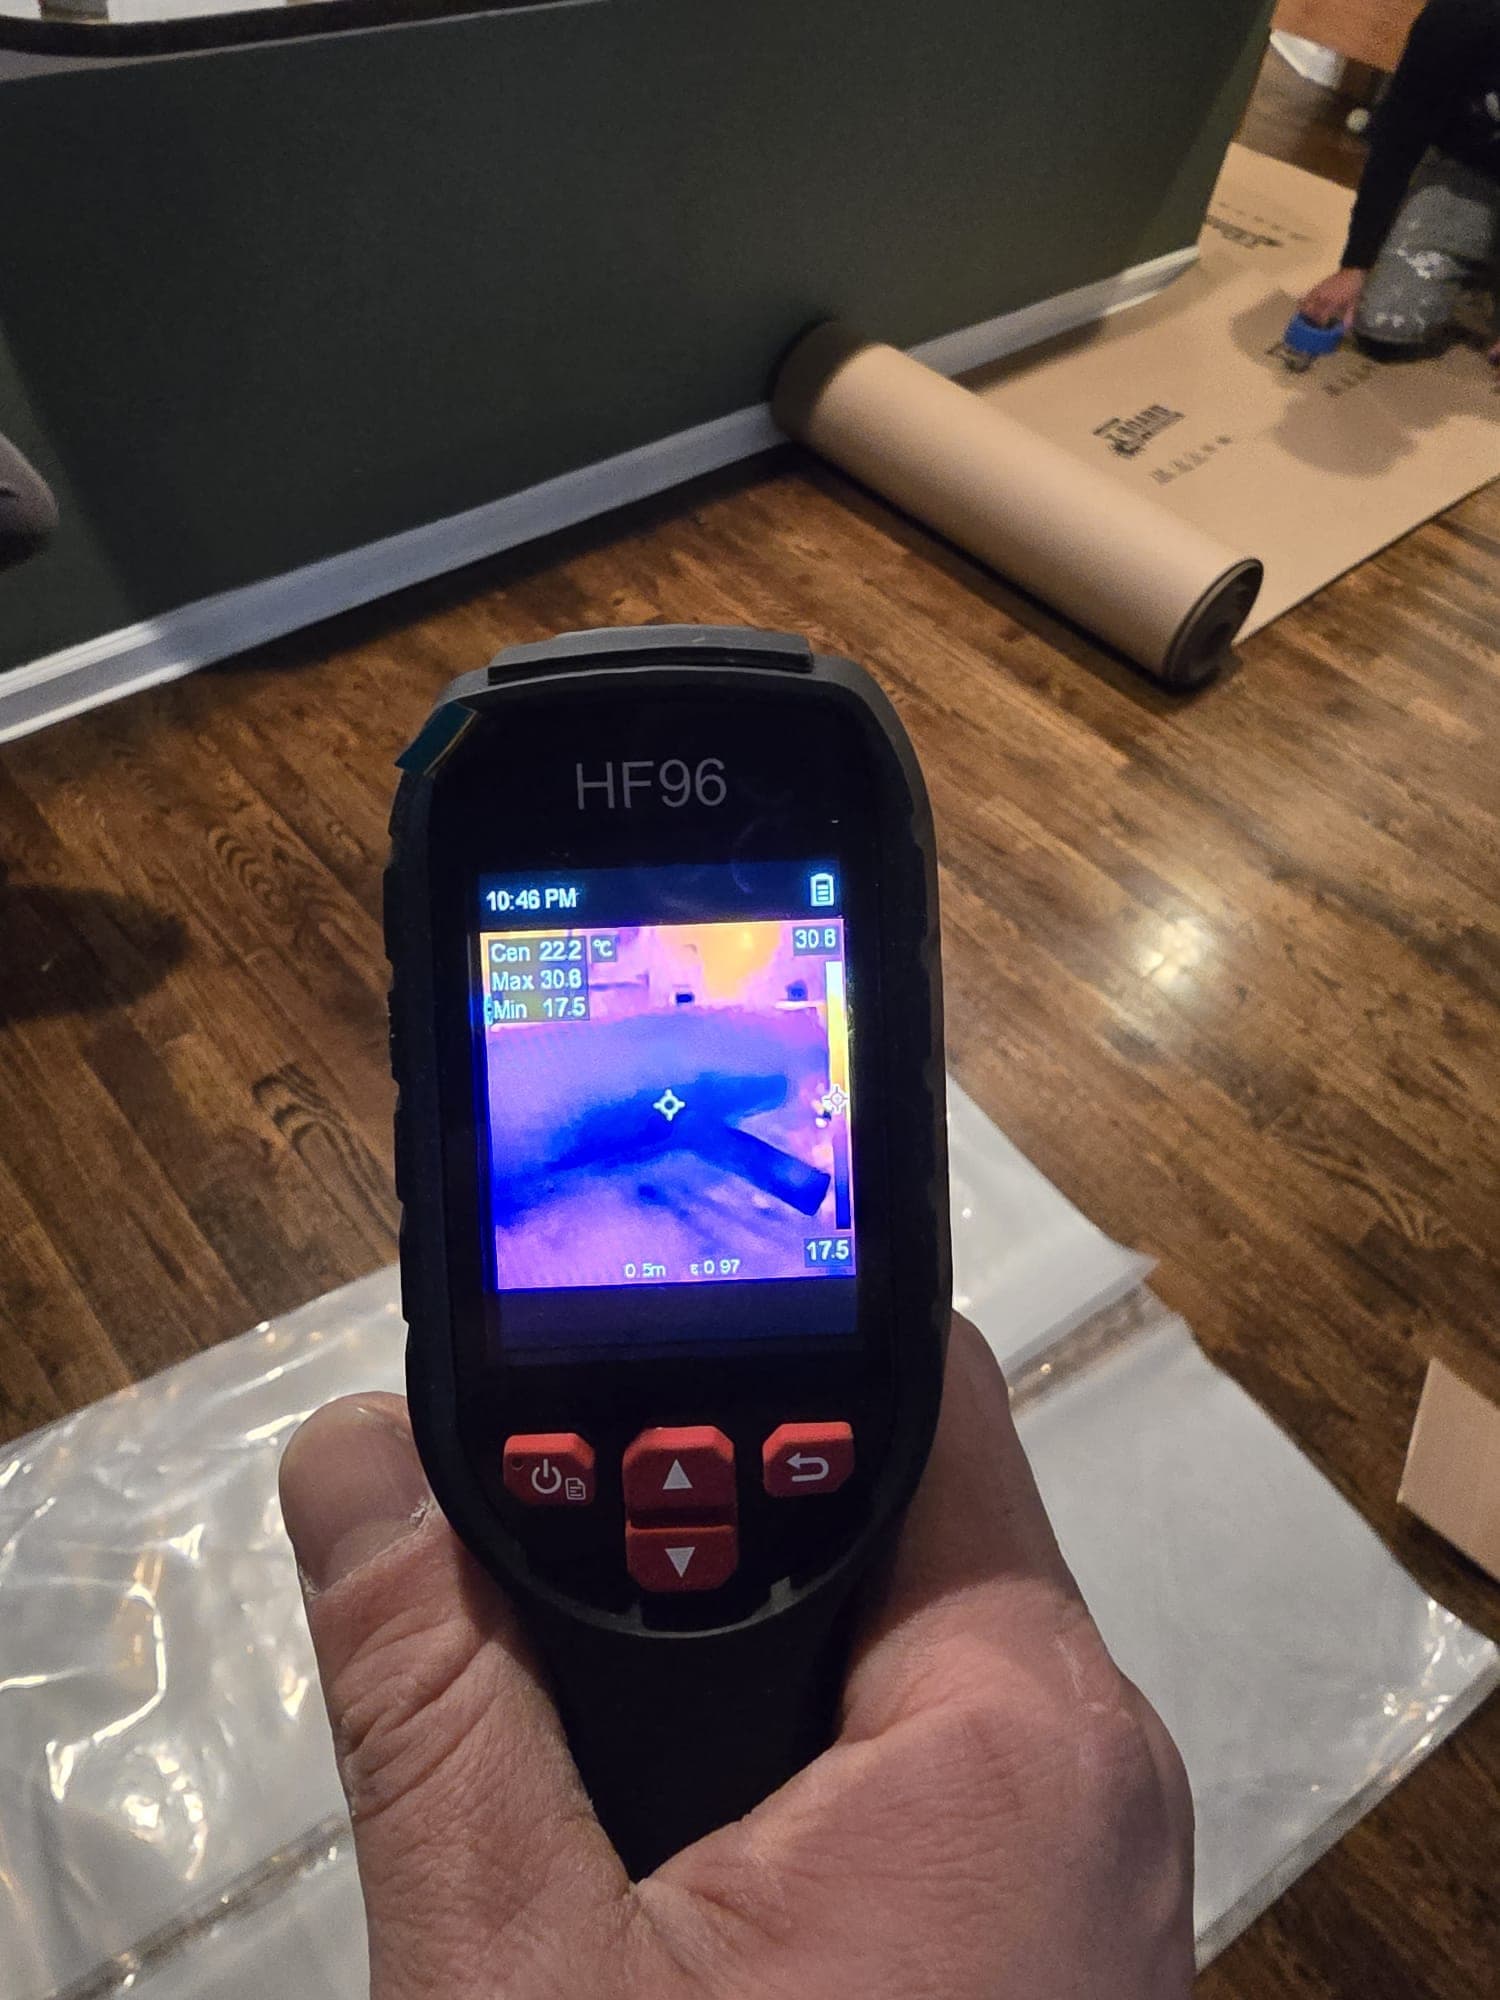
Photos before we touch anything, moisture readings in every affected material, notes on the cause of loss, and daily drying logs once equipment is running. Your adjuster gets that whole file, recorded as the work happens.
- 03
We work with your adjuster
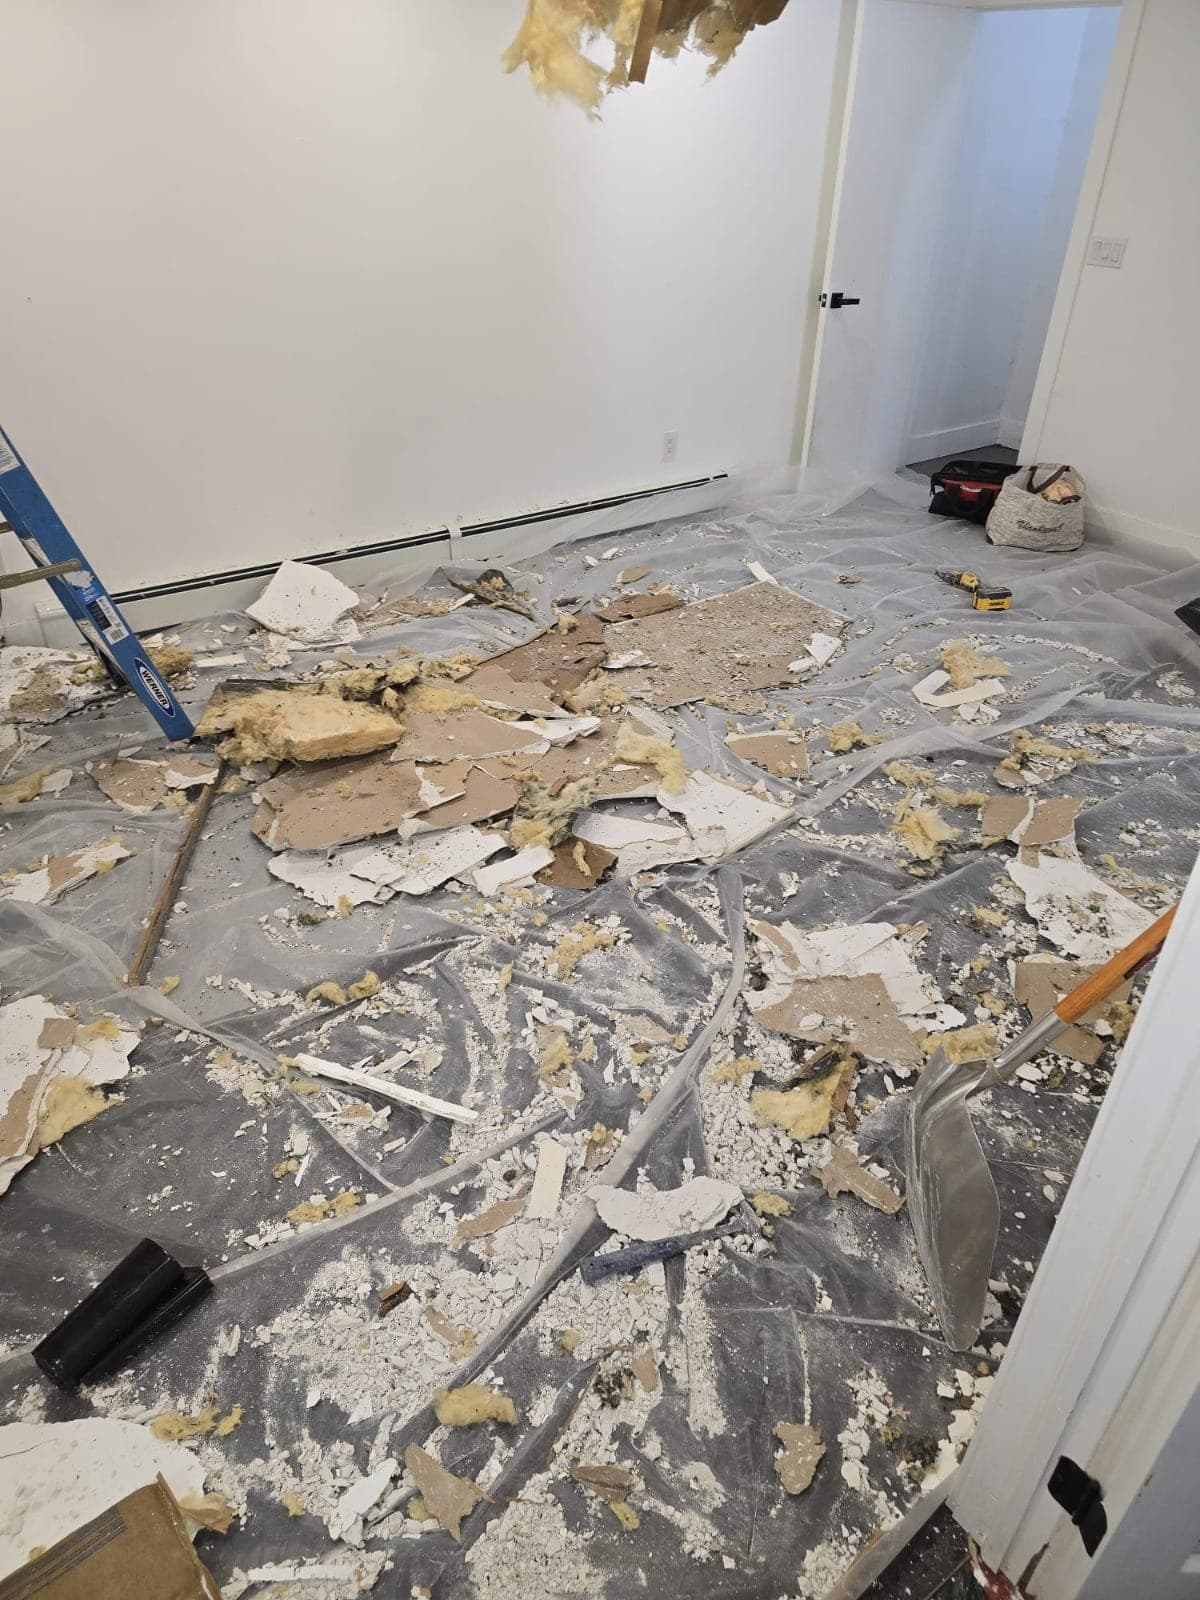
We walk the adjuster through the scope, answer the technical questions, and back every line item with readings and photos. If the estimate is missing lines, we request supplements in writing, and most gaps close once the carrier sees the readings.
- 04
We bill the insurer directly
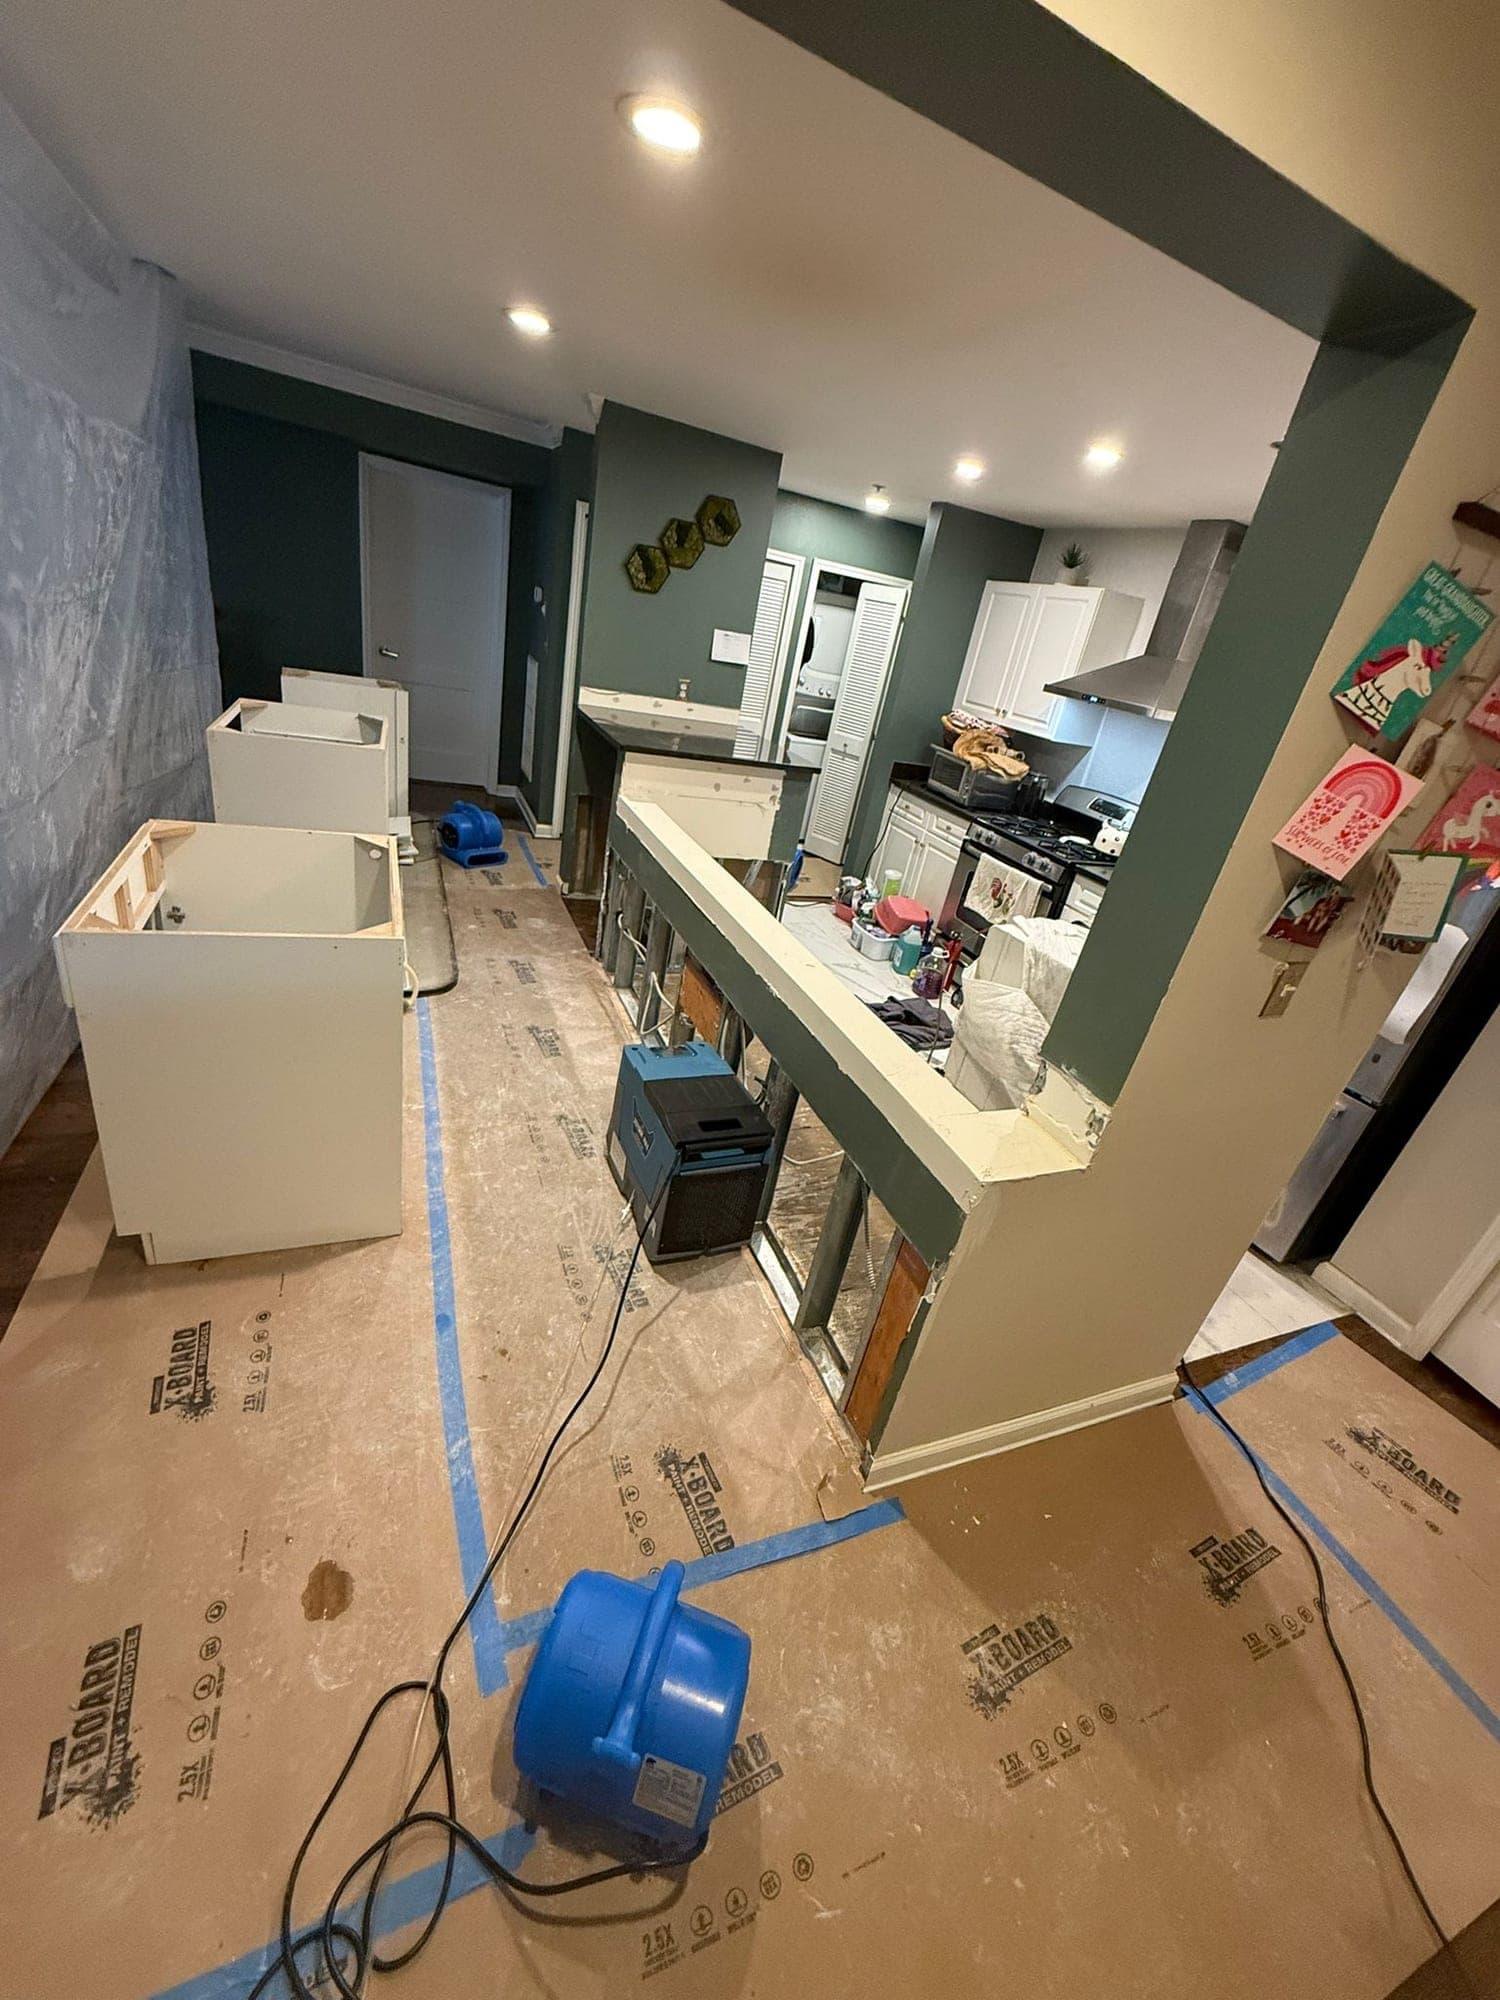
On covered water and mold claims, the bill goes from us to your carrier. You don't front the cost of mitigation and then wait on reimbursement. We handle the billing paperwork with your carrier.
- 05
You pay your deductible, nothing hidden
The deductible is the share of a covered loss you agreed to when you bought the policy, and it applies before insurance pays anything. We can't waive it, and nobody can without misrepresenting the claim to your carrier. After the free inspection you get a written estimate, so you and your agent can decide whether filing makes sense against your deductible.
Why the cause of loss matters
What your insurer will ask about the water
Most homeowners policies draw a line between sudden and accidental damage and gradual damage, and the cause of the water usually matters more to the carrier than the amount of it. Where your policy draws that line is your insurer's call, not ours. This is general background so you know why we document the source so carefully.
Insurers commonly treat as sudden & accidental
- A pipe that burst or froze and let go
- A water heater or appliance hose that failed
- An overflow that came through the ceiling
- Storm water that entered through sudden damage, like a wind-opened roof
Insurers commonly treat as gradual
- A slow leak that ran for weeks or months
- Seepage and groundwater coming through the foundation
- Damage traced to deferred maintenance
- Mold that grew from long-term humidity rather than a covered water event
The flood-policy caveat
Rising water from outside is generally excluded from homeowners policies entirely: a river over its banks, storm surge, surface runoff coming in at grade. Those need a separate flood policy, usually through the National Flood Insurance Program. If that's your situation, we still do the work and document it the same way, and the file records where the water came from, which is what your insurer uses to decide which policy applies. Your agent can tell you whether you carry flood coverage.
Every policy is different, so read yours or ask your agent. At the free inspection we record the cause of loss carefully and put it in your file. Whether the damage is covered is your insurer's decision to make from that record.
Not insurance advice. We're a restoration contractor, not a public adjuster or insurance agent. Coverage decisions belong to your insurer, so confirm anything about your policy with your agent or adjuster.
Insurance questions we get most
Does homeowners insurance cover water damage?
That's a question for your insurer, and we say so on purpose. We're a restoration contractor, not a public adjuster or insurance agent, and only your carrier can tell you what your policy covers. In general terms, homeowners policies treat sudden and accidental damage, like a burst pipe or a failed water heater, differently from a slow leak that ran for months, and flooding from outside is usually a separate policy. That's why the cause of loss matters. When we inspect, we photograph and log what the damage shows, and that record goes to your insurer for their decision. Call your agent or your carrier's claim line to confirm coverage before you count on it.
Do you bill my insurance company directly?
Yes. On covered losses we bill your insurer directly, so you're not writing a large check and waiting for reimbursement. You pay your deductible and we settle the rest with the carrier, backed by the photos, moisture readings, and daily drying logs adjusters ask for. You don't need a claim to hire us, though. A lot of our residential work is paid directly by the homeowner.
Do I still have to pay my deductible?
Yes. The deductible is your agreed share of a covered loss, and it applies before insurance pays anything. Your declarations page or your agent has the exact number. Be wary of any contractor offering to waive or absorb it; that misrepresents the claim and can put you at risk. If the damage is small, we say so after the free inspection and give you the written estimate, so you and your agent can decide whether filing makes sense against your deductible.
Should I wait for the adjuster before you start work?
Usually no. Most homeowners policies require you to take reasonable steps to prevent further damage, and your agent or adjuster can confirm what yours says. Extraction and drying should start promptly instead of several days later, once materials have soaked through and mold has had time to start. We photograph and document everything before and during mitigation, so the adjuster sees what condition the property was in.
What documentation does an insurance claim need?
Four things: photos of the damage before work starts, moisture readings from every affected material, daily drying logs, and an itemized scope of what was done and why. We produce all of it as we work, and you get copies whether or not you file. If a failed part caused the loss, like a supply line or a burst hose, keep it, because adjusters often ask to see it.
What if my claim gets denied?
A denial is between you and your carrier, and we're not public adjusters, so we can't argue the claim for you. What we can do is hand you the complete file: photos from before work started, moisture readings, and notes on the cause of loss. Homeowners sometimes ask their carrier for a re-inspection with that documentation, and if you want someone to negotiate the claim on your behalf, that's a licensed public adjuster or an attorney. If the denial stands, we'll walk you through what the work requires and what can safely wait. The inspection and estimate cost nothing either way.
Start with the free inspection.
We look, take moisture readings, and photograph the damage, then tell you what you're dealing with and what the repair involves. Active water? Our emergency line answers six days a week.